If you didn’t have enough on your plate, add increased legal costs or social inflation to the list. What is social inflation? Social inflation has become a catch-all term for increased costs associated with insurance claims, primarily liability claim costs and associated litigation. These expenses have dramatically outpaced general economic inflation.
Key drivers of social inflation include:
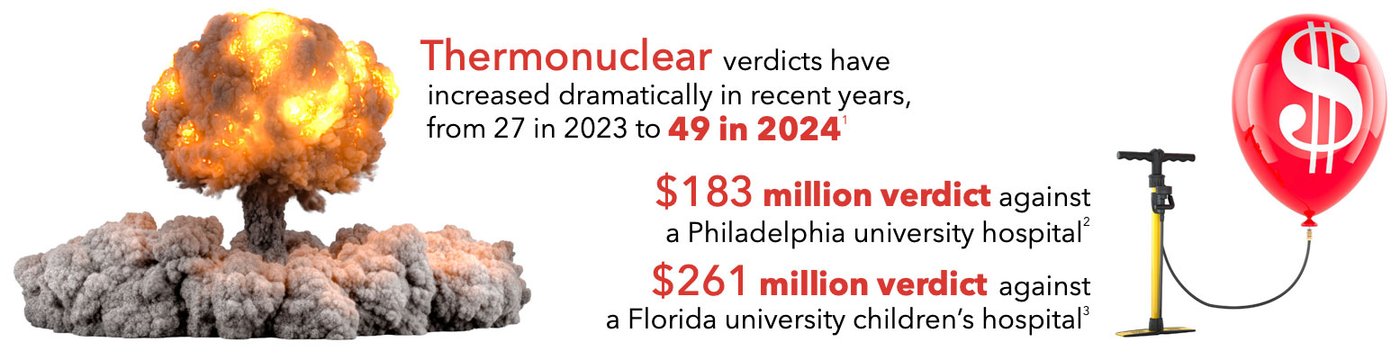
Large Jury Awards and Settlements: The rise of large claims has accelerated drastically. There has been a significant increase in claims over $10 million, which are referred to as “nuclear” verdicts. These large settlements are becoming so commonplace that a new term has been coined for settlements over $100 million: “thermonuclear” verdicts.
Legal and Litigation Trends: Third-party funded litigation is also having a direct impact on driving up the cost of lawsuits. Private equity money is flowing into litigation at an unprecedented rate. According to Westfleet Advisors, the U.S. litigation funding market is estimated to have over $16 billion in assets under investment. The market has more than doubled over the last five years and is expected to reach $50 billion globally over the next 10 years.4 Expanded definitions of liability are also driving increased costs.
Society’s Changing Views: Gone are the days when people assumed large corporations, including higher education institutions, would “do the right thing.” We are in an environment of distrust and negative sentiment. Access to information, valid or not, is instantly shared via social media. These sources tend to highlight the negative sentiments. This can influence jurors who ultimately award higher damages.
Legal Advertising: Drive down the highway in your favorite city, and you will notice a significant amount of advertising by personal injury attorneys “looking for business.” According to the American Tort Reform Association, legal service advertisements have increased by 39%, while at the same time the total quantity of advertisements has decreased by 4%.5
Increased Legal Costs: According to Thompson Reuters, hourly legal costs have reached record highs in 2025, with some of the top large law firms charging up to $3,400 to $4,000 an hour. Legal services rates are increasing by 5% to 7% annually.6
Why is higher education vulnerable?
Colleges and universities operate in a complex environment. Large universities are major employers with high visibility, managing thousands of students and employees across campuses—housing, academic buildings, dining, athletics, stadiums, utilities, and healthcare facilities. This creates legal risk in areas such as:
Campus Safety and Premises Liability
Politically Influenced Changing Regulations
Title IX and Civil Rights Litigation
Class Action and Antitrust Litigation
Employment and Wage Claims
Sexual Abuse and State Revivor Statutes
Medical Malpractice
Student Transportation
Athletic Participation
What is the financial impact to higher education?
Increasing Insurance Premiums – We are in a “soft“ insurance market for many coverages but not liability insurance, where premiums continue to rise. Even if your institution has good loss experience, you might be in a legal jurisdiction that isn’t favorable and end up with big insurance increases. Rising premiums have colleges and universities of all sizes looking for ways to mitigate these costs, including increasing deductibles or sharing more in the risk via a captive or other alternative program structure.
Reduced Insurance Capacity – There is a limited market for insurers willing to cover the liability exposure of colleges and universities, and this is unlikely to change soon. Most insurance companies are restricting the limits they are willing to offer. This means a more complex, expensive layered insurance program will be required to obtain sufficient limits as capacity shrinks.
Budgetary Pressures – As insurance rates and claims costs rise, the funding needed to cover insurance premiums must come from somewhere. If you increase deductibles or share the risk in another way, these costs will need to be budgeted. Accounting for the increased costs of social inflation will likely require reductions in other important areas, such as deferred maintenance, or it will be passed on to students through tuition increases.
Credit Rating Implications – Increased litigation expenses, exposure to potential litigation, and an unfavorable reputation from public litigation can all lead to negative credit rating changes. This results in increased borrowing costs, fewer lending options, and less flexibility with credit and financial markets.
Moodys, S&P Global Ratings, and Fitch have all issued negative outlooks for education in 2026.7
What can be done?
Here are four actionable strategies to mitigate social inflation.
Proactive Risk Management and Cooperation with In-House Counsel
Institutions can reduce exposure to lawsuits by implementing robust compliance programs with audits, providing regular training on EEOC and discrimination laws, conducting risk assessments, and ensuring an effective contract review process.
Clear Communication
Clearly written and communicated internal policies and procedures can prevent costly litigation.
A Reptile Theory trial is when the plaintiffs paint the defendant as a “bad actor” and aim to override logical, rational thinking with fear-based decision-making.
Documents like emails, letters, and texts become evidence in litigation. The more detailed the information, the more effective it will be in defending claims. Consistent messaging through official channels can prevent the spread of misinformation, which is damaging to the institution but helpful to the plaintiff.
Selecting the Right Partner
Aggressively selecting and managing outside legal counsel is one of the most important mitigators of social inflation. The right partner will work to counter aggressive plaintiff tactics and use data-driven strategies to prevent increased damages. The right partner is proactive, not just in response to claims, but also by reviewing policies and procedures in place to prevent incidents from becoming lawsuits as the first line of defense.
When selecting a law firm, consider the following:
Utilize a data-driven process. Ask for samples of litigation, strategies, and outcomes. Focus on results, not just reputation. Make sure they have local knowledge and experience. Ask what they are doing to defend against social inflation.
How are they leveraging predictive modeling and data to know which cases need more attention and more seasoned counsel?
What experience do they have taking cases to trial and effectively examining and vetting jurors?
How do they work early in the claim process to defend against “anchor” tactics? How do they establish a realistic case value early on to counter high-dollar demands?
How do they develop trial themes and humanization? They should work closely with you to humanize your focus on safety programs, compliance efforts, and community work. Anything that will counter juror anger and negative sentiment goes a long way to defending against a Reptile Theory trial strategy.
To the extent possible, determine if a case is third-party funded so you know what you are up against. Utilize discovery requests to uncover funding agreements, documents, funds received, or correspondence with financiers. Review state laws and check court rules, as some states and jurisdictions require disclosure. Look for signs–delays in settlement, other parties reviewing the case, or liens on settlements.
Timing Matters
Report matters as soon as possible! In many cases, institutions don’t want to report a matter to their insurer until they know it will develop into a claim. They feel that it will adversely affect loss experience and lead to higher premiums.
A more effective strategy is to discuss this with your insurance company as soon as possible. Insurers have seen every possible situation. They have insight that can help mitigate the exposure early in the process.
Take action today!
We are navigating a new legal landscape. This is not a temporary issue, and it requires a long-term strategic plan to address.
Colleges and universities that treat legal risk as a proactive strategic governance issue, not just as an insurance problem or an increased expense problem, will be best positioned to navigate the era of social inflation.
https://riskandinsurance.com/nuclear-verdicts-skyrocket-corporate-lawsuit-awards-surge116-to-31-3-billion-in-2024/
https://www.morrisjames.com/p/102jail/record-setting-medical
https://www.nytimes.com/2023/11/10/us/take-care-of-maya-trial-damages-kowalski.html
https://natlawreview.com/article/market-perspective-what-true-size-commercial-litigation-funding-industry
https://atra.org/white-paper-and-repo/legal-services-ads-2020-2024/
https://www.reuters.com/legal/litigation/lawyer-rates-surge-us-firm-charges-4000-an-hour-top-partners-2026-01-26/
https://www.highereddive.com/news/rating